Ask a better question.
Develop hypotheses, study market behaviour and evaluate trading ideas with statistical methods. Explain the mechanism, test the evidence and report the limitations.
A community for the research and engineering behind quantitative finance. Turn financial questions into testable, data-driven models.
QFA develops motivated students through hands-on learning, collaborative projects and an introduction to the quant industry. Research and Development work together to connect an idea with a reproducible result.
Develop hypotheses, study market behaviour and evaluate trading ideas with statistical methods. Explain the mechanism, test the evidence and report the limitations.
Create data pipelines, backtesting frameworks and simulated execution systems. Turn research into implementations with explicit costs, tests and risk controls.
Thirteen lessons across two semesters, supported by project work, industry exposure and simulated trading. Weekly sessions combine concepts with notebooks, simulations and discussion.
Algorithmic trading, returns and risk, market microstructure, and preparation for projects and quant careers.
Backtesting, derivatives, factor models, machine learning, statistical arbitrage, portfolio risk and fixed income.
Mixed teams develop a hypothesis, reproducible implementation, experiment record and honest evaluation.
Present your approach, results and limitations. Learn from strategy clinics and a simulated trading competition.
AY2026/27 programme outline. Teaching weeks are indicative; members receive confirmed session arrangements separately. Projects and the internal competition use simulated capital.
Weekly sessions of around two hours combine concepts, Python notebooks, simulations, discussion and short checks for understanding.
Teams define a question and baseline, challenge the results, and document the evidence and limitations in a research brief.
Development brings together code, tests and documentation so another team can understand, rerun and build on the work.
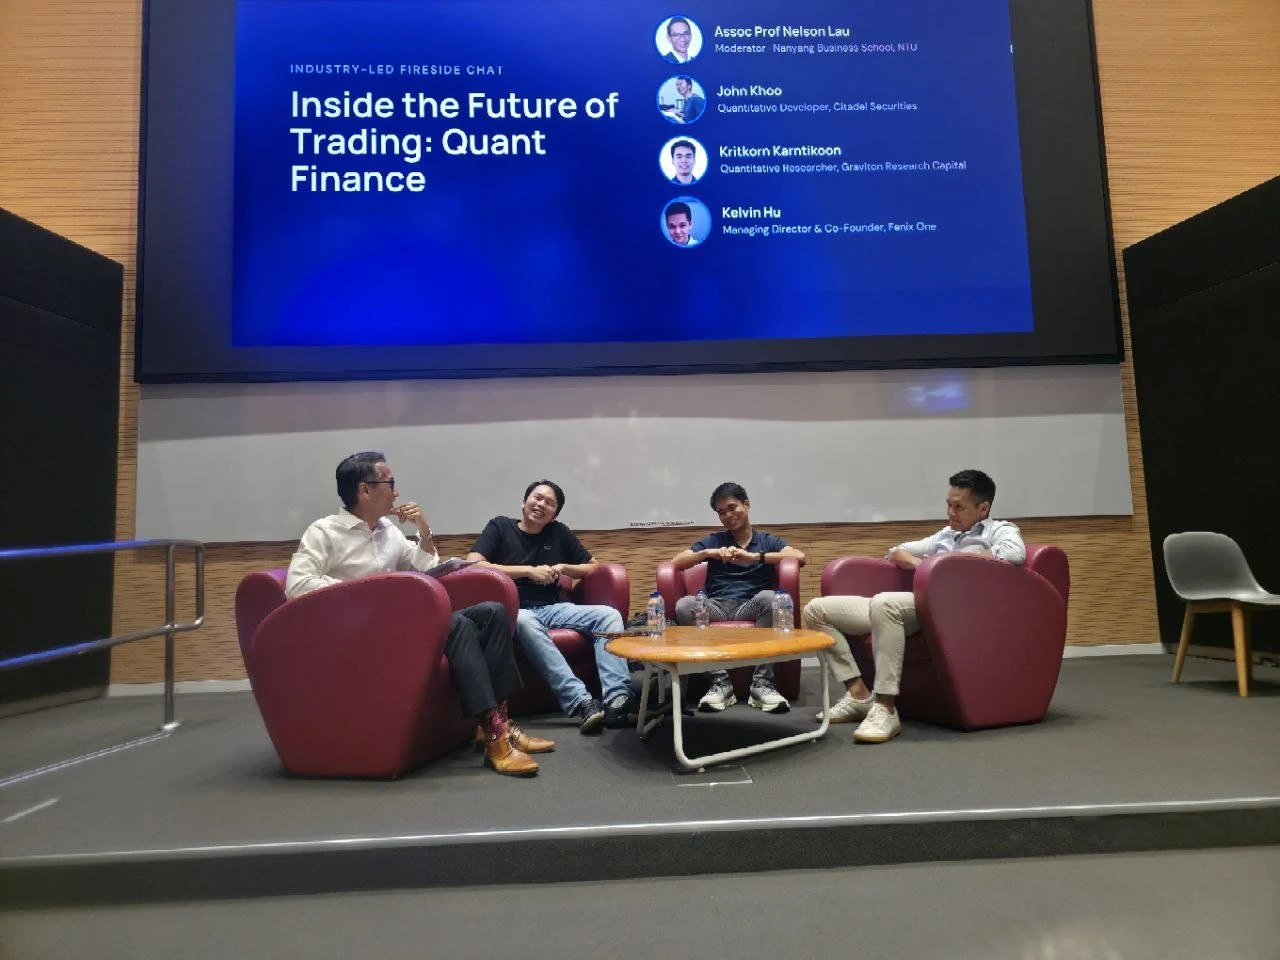 QFA / Panel & networking
Inside the world of algorithmic alpha: from research hypotheses and backtesting to live trading systems.
Explore the eventAn NTU-to-quant career conversation with NBS alumnus Marcus Foo and the Qube Research & Technologies recruitment team.
Explore the event
Head, Quantitative Finance
Interested in research, coding or financial markets? Contact the academy and follow NFC’s bulletin for the next intake.